If your accounts receivable team is sending more delinquent accounts to third parties than a year ago, you are not alone. Collection agencies are reporting record placement volumes, yet many of them say they are recovering less from each account. For credit managers, AR leaders and CFOs, this changes the question from “Who do we send these accounts to?” to “When do we send them, and who is actually equipped to collect?”
This guide explains what the latest industry data shows, why the traditional “send everything at 90 days” playbook is losing effectiveness, and how to choose a commercial debt collection agency or collection attorney in a tougher recovery environment.
What Record Placement Volumes Are Telling Us About Commercial Debt Collection
ACA International’s industry survey, published in February 2026, paints a clear picture. Sixty-four percent of firms saw higher account volumes in 2025, and 75% expect volumes to rise further. Nearly half (48%) expect double-digit growth. At the same time, 28% of firms reported that collectability declined despite the rising placements.
More accounts, lower recovery potential. That combination is a warning sign for any business that relies on third-party recovery to protect cash flow.
Several forces are likely behind the trend:
- Tighter business liquidity. When your customers struggle with their own cash flow, they pay slower and defend disputed invoices harder.
- Older accounts. The longer an invoice ages, the lower the odds of recovery. Accounts that arrive late are simply worth less to everyone.
- Agency capacity strain. When volume spikes, individual accounts get less attention unless the agency has the staff and technology to prioritize well.
- Higher insolvency risk. Rising bankruptcies mean more debtors with limited assets by the time a placement is made.
The takeaway: volume alone tells you nothing about results. The metric that matters is how much of your placed balance actually comes back.
Why “Send Everything at 90 Days” Is Losing Effectiveness
Many creditors still run a simple policy: once an invoice is 90 days past due, it goes to a collection agency. It is easy to administer, but it treats every account the same, and in a high-volume market that is expensive.
Consider what happens under a blanket rule:
- Good accounts wait too long. A solvent customer with a genuine dispute could have been resolved at day 45. By day 90, the relationship is strained and the debtor has deprioritized your invoice.
- Bad accounts wait too long, too. A customer showing signs of distress needs urgent action. Every extra week reduces the chance of being paid ahead of other creditors.
- Agencies receive a mixed, aged pile. A batch that combines easy and hopeless accounts makes it harder for the agency to apply the right strategy, and harder for you to judge its performance.
In short, a uniform timeline wastes the one advantage you control: timing.
Earlier, Segmented Placement: A Smarter Approach to Accounts Receivable Recovery
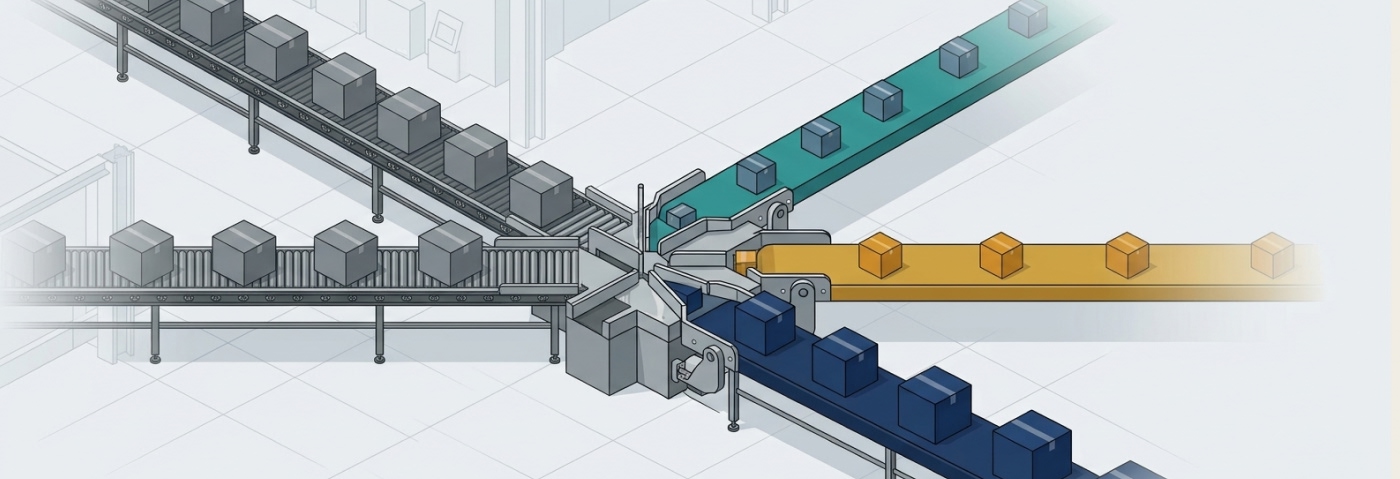
Instead of one trigger date, leading AR teams segment accounts and place them on different schedules. A practical framework looks like this:
- Segment by balance. High-value invoices may justify earlier escalation to a collection attorney. Small balances may suit a lower-cost agency workflow.
- Segment by debtor behavior. Customers who ignore communication, change contacts or make broken promises to pay deserve faster escalation than customers who are simply slow.
- Segment by dispute status. Disputed invoices often need legal review or documentation work rather than standard collection calls.
- Segment by debtor risk. Signs of financial distress, such as liens, lawsuits or payment delays to other vendors, are a reason to move quickly.
Earlier placement does not mean giving up on your internal process. It means defining clear criteria for when an account leaves your team’s hands, based on its likelihood of payment rather than the calendar alone.
Collection Agency vs. Collection Attorney: Matching the Account to the Right Partner
The ACA survey also found that law firms showed the strongest liquidation performance, with 53% reporting improvement. That does not mean every account should go to an attorney, but it does support a more deliberate split:
- Collection agencies are generally well suited to high-volume, lower-balance accounts where persistent outreach and negotiation resolve the debt.
- Collection attorneys are often the better choice for larger balances, disputed invoices, uncooperative debtors or situations where legal action (demand letters, litigation, judgment enforcement) is a realistic next step.
Many creditors benefit from using both, with a clear escalation path from one to the other. The key is choosing based on the account profile, not habit. And when an account does need an attorney, searching for debt collection lawyers near me is rarely the best way to find the right one, because location matters far less than commercial experience and track record.
7 Questions to Ask Before You Choose a Collection Agency
When volumes are high, every agency will tell you it is ready for your accounts. These questions separate marketing from capability.
- How do you score and prioritize accounts? Look for a defined method that uses data such as balance, age and debtor behavior, rather than “we work every account.”
- What is your liquidation rate for commercial accounts like mine? Ask for results by account age, balance band and industry, not just a headline average.
- Do you specialize in commercial debt collection? Consumer collection and B2B collection follow different rules, relationships and negotiation dynamics.
- What is your capacity right now? Ask how many accounts each collector handles and how the agency is managing growing volumes.
- What is your process for disputes? Commercial invoices are often contested. A good partner documents, escalates and resolves disputes instead of returning them unworked.
- When do you recommend legal action, and who makes the decision? You should control litigation spending, with clear thresholds and approvals.
- How do you report and remit? Look for transparent reporting, regular updates and defined remittance timelines.
Collection Agency Evaluation Scorecard
Use this scorecard to compare vendors side by side. Rate each criterion from 1 (weak) to 5 (strong), multiply by the weight, and compare totals.
| Criterion |
What to look for |
Weight |
| Account scoring |
Documented, data-driven prioritization |
20% |
| Commercial specialization |
Proven B2B collection experience in your industry |
20% |
| Liquidation performance |
Verifiable results by age and balance band |
20% |
| Legal capability |
In-house counsel or a strong attorney network |
15% |
| Capacity and staffing |
Reasonable account load per collector |
10% |
| Reporting and transparency |
Clear dashboards, regular updates |
10% |
| Fee structure |
Competitive, transparent contingency or flat fees |
5% |
A vendor scoring below 3 on scoring, specialization or liquidation performance should raise concern, regardless of how competitive its fees are. A lower commission on a smaller recovery is rarely a bargain.
How Retrievables Helps You Find the Right Collection Attorney or Agency
Building a vendor evaluation process takes time, and most finance teams do not have it to spare. This is where Retrievables comes in.
Retrievables is a platform focused exclusively on commercial debt collection. We help businesses find the collection attorney or agency best suited to each case, rather than leaving you to search blindly or send every account to the same provider.
Here is how it works for your team:
- Match by case, not by guesswork. Share the details of your claim, such as balance, debtor location and industry, and get connected with collection professionals who handle accounts like yours.
- Compare qualified options. Instead of vetting dozens of firms, you can focus on partners with relevant commercial experience.
- Support earlier, segmented placement. With a clear path to the right attorney or agency, you can escalate accounts when it makes sense instead of waiting for an arbitrary 90-day cutoff.
- Stay focused on commercial claims. Our focus is B2B recovery, which is exactly where specialization matters most.
If you are reviewing your recovery strategy ahead of Q4, Retrievables can help you move from a default process to a deliberate one. Start with Retrievables and find the right partner for your next placement.
Conclusion: Choose for Collectability, Not Just Capacity
Record placement volumes are a sign of pressure, not performance. As 28% of agencies report declining collectability, creditors who keep sending every account at 90 days to whichever agency is available are likely to see weaker returns.
A better approach has three parts: segment your accounts, place them earlier when the risk calls for it, and hold every agency to the same standards on scoring, specialization and liquidation. Use the scorecard above to make those standards concrete, and match each account to the agency or attorney best equipped to collect it.
Source: ACA International industry survey, published February 13, 2026.
FAQ
When should I send an account to a commercial debt collection agency?
There is no universal date. Many creditors use a combination of invoice age, balance, debtor behavior and risk signals rather than a fixed 90-day rule. Higher-risk or higher-value accounts often warrant earlier action.
What is a good liquidation rate for a collection agency?
Rates vary widely by account age, balance and industry, so ask for results that match your portfolio rather than a single headline number. Compare several vendors using the same account profile.
Should I use a collection agency or a collection attorney?
Agencies often suit high-volume, lower-balance accounts. Attorneys are frequently better for larger, disputed or uncooperative accounts where legal action may be needed. Many businesses use both.
How does Retrievables help me choose a collection agency?
Retrievables focuses on commercial debt collection and helps you find the collection attorney or agency best suited to your specific claim.